

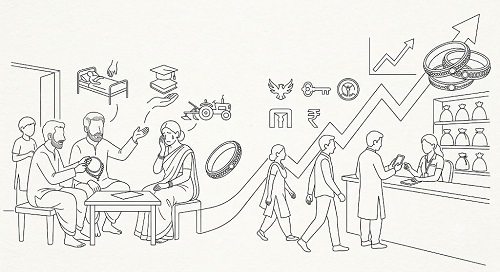
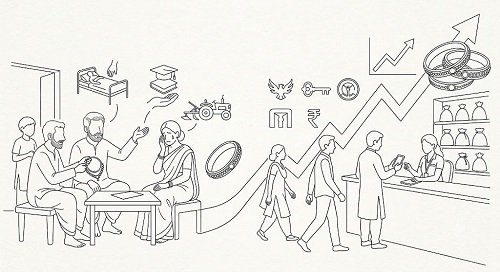
For many years, gold has held important value as a store of wealth among Indian families. But with changing times, the mindset of people has changed. Due to which the, gold which was lying in lockers and cupboards has started being used to raise money.
 |
Gold loans are rising rapidly in India as people unlock the value of their gold to fund education, healthcare, business and other financial needs
Gold loans are seeing rapid growth in India as there has been an increase in borrowers pledging jewellery to meet the funding requirements instead of selling it. The recent data reflects that this trend has accelerated in 2026.
Credit against jewellery by NBFCs, including housing finance companies, has increased to 68.5% year-on-year in July 2026 as compared to 43.9% in the previous year. Bank credit against gold jewellery also increased by 88.1% year-on-year.
At the end of July, outstanding gold-backed credit was around Rs. 3.54 lakh crore for NBFCs and Rs. 5.52 lakh crore for banks. Gold loans were also amongst the fastest-growing retail loan categories for NBFCs during the month.
Rising Gold Prices have Increased Borrowing Capacity
One of the major reasons behind the surge is the high increase in gold prices. Domestic gold prices were very high in 2026 compared to the previous year. During Q2 2026, India’s domestic gold price rose by 59% compared to the previous year, despite price easing from its earlier peaks. This played an important role in increasing the demand for gold loans.
The amount you can borrow against gold jewellery depends partly on the gold value and applicable loan-to-value (LTV) limit. With a rise in gold prices, you can get a loan of a higher amount with the same quantity of gold.
People Don’t have to Sell their Gold
Indian families are deeply connected to their gold jewellery due to its financial and emotional value.
By selling gold, you can get cash on an instant basis, but the asset is gone forever. A gold loan, however, works very differently. A borrower has to pledge the jewellery as collateral to get a loan. After the loan is repaid, the collateral is released and given back to the borrower.
This can make gold loans quite attractive when people need funds for short-term needs like medical emergencies, education, business needs, or any other large expenditures.
The trend is particularly notable as gold recycling has reduced despite being 60% higher YoY. Gold holders no longer want to sell their gold for cash and have increasingly opted for collateralised borrowing to monetise their holdings instead.
Gold Loans Are Secured
Another important reason for the growth in gold loans is their secured nature. A gold loan is backed by physical gold pledged with the lender. This is quite different from a personal loan where there is no asset involved.
Collateral gives extra security to lenders against probable repayment concerns. It also helps borrowers to get credit by using an asset they already own.
This is quite helpful for those individuals who don’t have a strong credit history or for those who find unsecured borrowing quite expensive.
Banks are Increasing their Presence
Gold lending was previously an important business for specialised NBFCs. But over time, things have changed, and now even banks are increasingly participating in this segment.
The recent data shows that bank lending against gold jewellery has increased very fast, with outstanding credit reaching approximately Rs. 5.52 lakh crore by July 2026. Earlier, at the end of May 2026, the outstanding gold loans stood at around Rs. 5.1 lakh crore for banks, which reflected 105% YOY growth.
Unsecured Lending is Being Watched Closely
The rise in gold loans should also be viewed against the broader changes that are occurring in India’s retail credit market. The RBI has brought certain measures in recent years for strengthening risk management around unsecured consumer credit. As lenders start focusing on risks associated with unsecured borrowing, secured products can become an important part of their lending strategy.
This never means that people are not taking online loans or other unsecured credit. But the rise in gold loans shows that both lenders and borrowers are increasingly using existing assets to access funds.
RBI Has Standardised Gold Loan Rules
The rapid expansion in gold-backed lending has also been accompanied by a stronger regulatory framework. The RBI’s Lending Against Gold and Silver Collateral Directions, 2025 introduced standardised requirements that cover areas such as valuation, assaying, LTV limits and the release of pledged collateral.
For consumption loans, the framework permits maximum LTV ratios of:
-
85% for loans up to Rs. 2.5 lakh, up from the long-standing 75% cap.
-
80% for loans above Rs. 2.5 lakh and up to Rs. 5 lakh
-
75% for loans above Rs. 5 lakh
These requirements are intended to create greater consistency and transparency in gold-backed lending. For smaller borrowers and households in semi-urban and rural India, this is a direct lift in credit accessibility.
The Bigger Picture
The rapid rise in gold loans reflects the changing role of gold in Indian households. Gold is now not just considered an asset which is purchased, stored, and passed on to generations. It is also used as collateral to get access to formal credit.
With NBFC gold-backed lending rising 68.5% YOY in July 2026 and bank lending against gold jewellery also expanding rapidly, the importance of gold loans has increased in India’s retail credit market.
The underlying idea is simple: Instead of selling gold when cash is required, households can now use it as collateral to unlock liquidity while retaining the possibility of getting the jewellery back after repayment.

